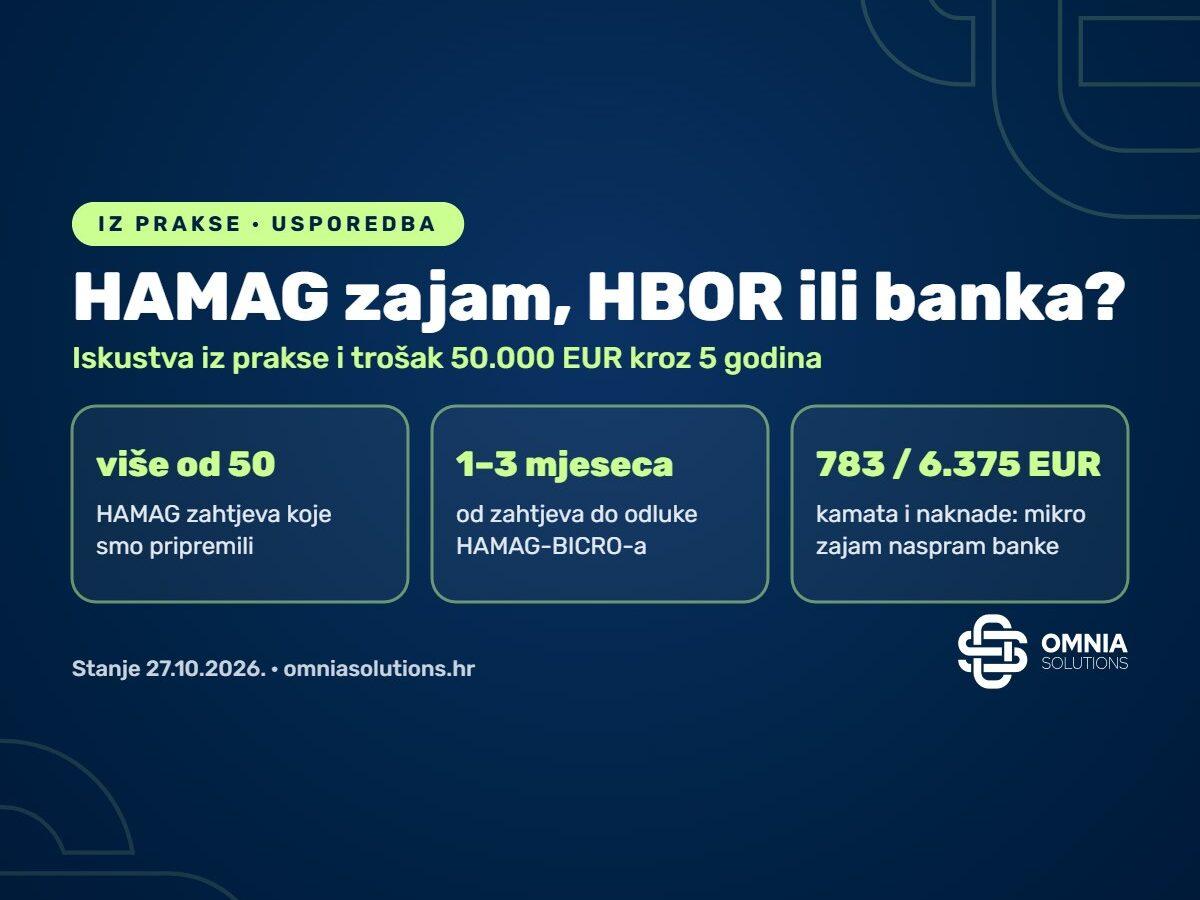
Omnia Solutions has prepared more than 50 applications for loans from HAMAG-BICRO (Croatian Agency for SMEs, Innovations and Investments) and more than 10 applications for loans from HBOR (Croatian Bank for Reconstruction and Development). More than 90% of the HAMAG applications we prepared were approved, and the time from receipt of the application to the decision was usually 1 to 3 months. For HBOR loans through a commercial bank, in our experience the decision came in about 6 months. The most common reasons why applications fail are a blocked account or debt to the state, and an investment paid before the application. On an example of EUR 50,000 with a 5-year repayment period, the Micro Loan for Growth and Inclusion (Mikro zajam za rast i uključenost) costs EUR 782.91 in interest, the HBOR loan for young people, women and start-ups through a bank no more than EUR 5,122.38, and a bank loan from EUR 6,375.20 to 9,864.07, including the processing fee.
This article sets out our figures from practice, the two mistakes that most often cause an application to fail, and a calculation of the total cost of four funding sources on the same example. We checked the programme conditions on the HAMAG-BICRO and HBOR websites, and the average bank interest rate in the statistics of the Croatian National Bank (HNB), on 27 October 2026. We describe all open HAMAG-BICRO programmes in the guide HAMAG-BICRO loans 2026, and the HBOR programmes in the guide HBOR loans for entrepreneurs 2026.
Our experience in figures
| Indicator | Omnia Solutions |
|---|---|
| Applications for HAMAG-BICRO loans that we prepared | more than 50 |
| Share of HAMAG applications approved | more than 90% |
| From receipt of a HAMAG application to the decision | usually 1 to 3 months |
| Applications for HBOR loans that we prepared | more than 10 |
| From submission of an HBOR application to the bank to the decision | about 6 months |
HAMAG-BICRO approves the loan directly, without a bank as intermediary. For an HBOR loan through a bank, the longer timeline should be taken into account already when planning the investment, especially if the supplier wants a quick order.
Two mistakes that most often cause applications to fail
Blocked account or debt to the state
The conditions are strict and do not look only at the current situation. For the micro loan, for example, the applicant’s account must not be blocked, and their current account must not have been blocked continuously for more than 30 days in the last 6 months. Nor may the applicant have outstanding obligations to the state, unless a rescheduling has been agreed with the state. The application must be accompanied by a certificate from the Tax Administration confirming that there is no debt, or an account statement (knjigovodstvena kartica) not older than 30 days.
- Before submitting, check your status in ePorezna, the Tax Administration’s online service, and settle even a small debt, for example an outstanding contribution or interest.
- If the debt has been rescheduled, attach proof of the agreement with the Tax Administration.
- If the account was blocked continuously for more than 30 days in the last 6 months, the condition is not met even after the block is lifted, so it is better to wait until that period has passed.
Investment paid before the application
HAMAG-BICRO loans do not finance the refund of previously paid obligations or investments that are physically completed. If the equipment has already been paid for with your own money, the loan cannot cover that cost. For the HBOR energy efficiency loan, for example, only costs incurred after the application is submitted and paid after the loan decision are refunded, and the rules of other programmes should be checked before the first payment.
- Offers or pro forma invoices are enough for the application, and the payment to the supplier should be planned for after the decision.
- If the supplier asks for an advance payment, agree a payment deadline that matches the disbursement of the loan.
- Do not complete the investment until the application is approved, because a completed investment can no longer be financed.
Cost comparison on an example of EUR 50,000
EUR 50,000 is the only amount that fits all four sources. The micro loan goes up to EUR 50,000, the Small Loan for Women Entrepreneurs and Start-ups (Mali zajmovi za žene poduzetnice i poduzetnike početnike) starts at EUR 25,001, and the HBOR loan for young people, women and start-ups through a bank starts at EUR 50,000. The calculation assumes an investment in equipment, a single disbursement and a 1-year grace period in which only interest is paid, except for HBOR in the second comparison, where the grace period is 3 years.
Comparison 1: all sources with a 5-year repayment period
| Source | Instalment after the grace period | Total interest | Processing fee | Total cost |
|---|---|---|---|---|
| HAMAG-BICRO micro loan, 0.5% | EUR 3,158.31 quarterly | EUR 782.91 | none | EUR 782.91 |
| HAMAG-BICRO Small Loan for Women Entrepreneurs and Start-ups, 0.5% fixed (currently closed) | EUR 3,158.31 quarterly | EUR 782.91 | none | EUR 782.91 |
| HBOR, Entrepreneurship of Young People, Women and Start-ups (Poduzetništvo mladih, žena i početnika), through a bank, up to 3.00% fixed | EUR 1,106.72 monthly | EUR 4,622.38 | EUR 500.00 | EUR 5,122.38 |
| Bank loan, 3.80% | EUR 1,124.48 monthly | EUR 5,875.20 | EUR 500.00 | EUR 6,375.20 |
| Bank loan, 6% | EUR 1,174.25 monthly | EUR 9,364.07 | EUR 500.00 | EUR 9,864.07 |
With the same repayment period, HAMAG-BICRO loans cost about EUR 5,600 to 9,100 less than a bank loan, and the HBOR loan through a bank about EUR 1,300 to 4,700 less. The quarterly HAMAG loan instalment of EUR 3,158.31 corresponds to setting aside about EUR 1,052.77 a month.
Comparison 2: the longest term for each source
| Source and repayment period | Instalment after the grace period | Total interest | Processing fee | Total cost |
|---|---|---|---|---|
| Micro loan, 5 years (longest term) | EUR 3,158.31 quarterly | EUR 782.91 | none | EUR 782.91 |
| Small loan for women and start-ups, 10 years | EUR 1,421.24 quarterly | EUR 1,414.68 | none | EUR 1,414.68 |
| HBOR through a bank, 12 years with a 3-year grace period | EUR 528.85 monthly | EUR 11,615.48 | EUR 500.00 | EUR 12,115.48 |
| Bank loan, 3.80%, 7 years | EUR 777.71 monthly | EUR 7,895.20 | EUR 500.00 | EUR 8,395.20 |
| Bank loan, 6%, 7 years | EUR 828.64 monthly | EUR 12,662.40 | EUR 500.00 | EUR 13,162.40 |
A longer term lowers the instalment but increases the total interest. The 12-year HBOR loan has the lowest instalment among the loans with monthly repayment, EUR 528.85, but costs EUR 12,115.48 in total, more than a bank loan at 3.80% over 7 years. The 10-year small loan has a quarterly instalment of EUR 1,421.24, or about EUR 473.75 a month, and the total interest is only EUR 1,414.68.
A principal write-off changes the calculation
- Micro loan: up to 30% of the principal drawn, in the example up to EUR 15,000, with regular repayment and the additional employment of a person with a disability, a person aged 55 or over, a long-term unemployed person or a young person up to 29 years of age without work experience, on a permanent full-time contract, for at least 12 months. Before being hired, that person must have been unemployed for at least 30 days, employment aid from the Croatian Employment Service (HZZ) must not be used for them, and the total number of employees must not fall below the number at the time of application. The write-off does not apply to a self-employed owner.
- Small loan for women and start-ups: up to 50%, in the example up to EUR 25,000. For each newly employed person, 10% of the principal is written off, and 15% if the person is a woman and/or a person younger than 30.
- The HBOR loan for young people, women and start-ups and the bank loan have no principal write-off.
The write-off applies only to the outstanding part of the principal, and the employment condition also means the cost of a salary. It therefore makes sense to factor it in when you plan to hire anyway, and the write-off request should be submitted while the remaining debt is still large enough.
What the tables do not show
- Who can apply. The micro loan is intended for micro and small companies and sole proprietorships younger than 3 years, and for those whose majority owners belong to vulnerable groups. The HBOR programme is intended for young entrepreneurs (majority owners younger than 41), women entrepreneurs and start-up entrepreneurs, and also for investments in assisted areas and hilly and mountainous areas. A bank loan has no such restrictions, but depends on creditworthiness.
- What is financed. The micro loan does not finance real estate or the fit-out of business premises, and working capital may make up no more than 30% of the loan. HBOR through a bank can finance up to 100% of the investment excluding VAT, with working capital of up to 30%.
- Collateral. For the micro loan, HAMAG-BICRO requires promissory notes (zadužnice) from the borrower and the owner and, depending on the risk assessment, other instruments. For a bank loan and an HBOR loan through a bank, the bank determines the instruments, and a bank loan can also be covered by a HAMAG-BICRO guarantee.
- Speed. In our experience, HAMAG-BICRO decides within 1 to 3 months, and HBOR through a bank within about 6 months. For a bank loan without HBOR, the time depends on the bank.
- Availability. The small loan for women and start-ups is temporarily closed because the funds have been used up, and by 27 October 2026 HAMAG-BICRO had not published a reopening date. The micro loan and the HBOR programme for special segments are accepting applications.
Which source for which investment
- A young company or sole proprietorship, or an owner from a vulnerable group, with an investment in equipment of up to EUR 50,000: micro loan, if the activity is not excluded from the programme.
- A woman entrepreneur or start-up with an investment of EUR 25,001 to 100,000: the small loan, when it reopens. Until then, for investments of EUR 50,000 and more, the HBOR programme through a bank, at an interest rate of up to 3.00%, and for smaller ones the micro loan, if the company meets its conditions.
- A young entrepreneur, woman or start-up with an investment of EUR 50,000 to 400,000: the HBOR programme for special segments, through a bank and for up to 100% of the investment excluding VAT.
- A company that does not meet the conditions of any programme: a bank loan, preferably with a HAMAG-BICRO guarantee, and for larger investments also HBOR loans, some with a write-off of up to 50% of the principal.
We compare all the options for young people, women and start-ups in the guide Aid and loans for young people, women and start-up entrepreneurs 2026.
Who prepares the applications
At Omnia Solutions, loan applications are managed by co-founder and director Matija Vlahovski, who has more than 10 years of experience in lending and financial advisory, including preparing loan proposals at a commercial bank. We prepare the application and the documentation on a turnkey basis. Read more on the pages HAMAG-BICRO loans: advice and application and HBOR loans: advice and application preparation.
Choosing between a HAMAG loan, HBOR and a bank?
Let us check which source is the cheapest for your investment and whether you meet the conditions
In the introductory call we go through the investment, the status of your account and your obligations to the state, and the payment plan, so that the application does not fail on a formal condition. The introductory call is free. Email or call us.
Frequently asked questions
How long does HAMAG loan approval take?
In our experience, it usually takes 1 to 3 months from receipt of the application to HAMAG-BICRO’s decision. The time depends on the number of applications in the programme and on whether the documentation is complete. For HBOR loans through a bank, the decision came in about 6 months.
Why does HAMAG-BICRO reject loan applications?
The most common reasons we see in practice are a blocked account or debt to the state, and an investment paid before the application. For the micro loan, the account must not have been blocked continuously for more than 30 days in the last 6 months, and the loan does not finance the refund of previously paid obligations or completed investments.
Is a HAMAG loan better value than a bank loan?
In the example of EUR 50,000 with a 5-year repayment period, the micro loan costs EUR 782.91 in interest and has no approval fee, while a bank loan at an interest rate of 3.80 to 6% with a 1% fee costs from EUR 6,375.20 to 9,864.07. The micro loan also allows a write-off of up to 30% of the principal drawn if a person from the prescribed vulnerable groups is additionally employed.
Is the HBOR loan for young people cheaper than a bank loan?
With the same 5-year term, the HBOR loan through a bank at the maximum interest rate of 3.00% costs EUR 5,122.38, and a bank loan from EUR 6,375.20 to 9,864.07. With the longest term of 12 years, the instalment falls to EUR 528.85 a month, but the total interest rises to EUR 11,615.48.
Can I apply for the small loan for women entrepreneurs and start-ups now?
No. The programme is temporarily closed because the funds have been used up, and by 27 October 2026 HAMAG-BICRO had not published a reopening date. Young companies can look into the micro loan of up to EUR 50,000, and women entrepreneurs, young people and start-ups into the HBOR programme for special segments.
How many of the applications prepared by Omnia Solutions were approved?
Of the more than 50 applications for HAMAG-BICRO loans that we prepared, more than 90% were approved. This is no assurance for a new application, because HAMAG-BICRO decides according to the programme conditions and the applicant’s situation.
Sources
- HAMAG-BICRO: Micro Loan for Growth and Inclusion
- HAMAG-BICRO: Small Loans for Women Entrepreneurs and Start-ups and Decision on the adoption of the programme, Official Gazette NN 98/2025
- HBOR: Entrepreneurship of Young People, Women, Start-ups and Other Special Segments
- HNB: interest rate statistics of credit institutions for July 2026
- Omnia Solutions: data on the applications we prepared, as of 27 October 2026.
The programme conditions are summarised from official sources as of 27 October 2026 and may change. The calculations are for information only and are not an offer. The actual cost depends on the lender’s decision, the interest rate on the day the application is received and the repayment schedule.