Principal write-off on the Small Loans for Industrial Transition: how it is calculated and what it is worth

Updated on 30 October 2026. This article has been turned into a guide to the principal write-off. Deadlines, conditions and the eligibility check with your municipality or town are on our main page about the Small Loans for Industrial Transition.
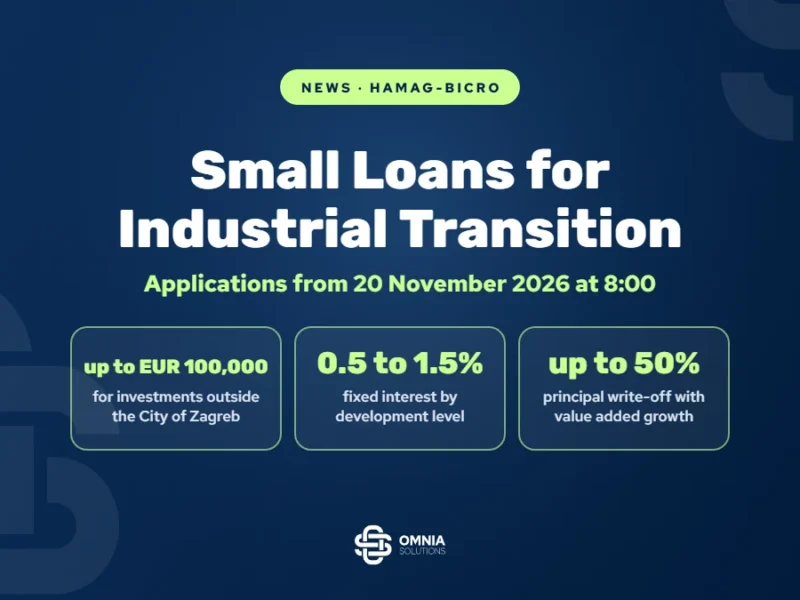
With HAMAG-BICRO’s Small Loans for Industrial Transition, up to 50% of the principal used is written off. The write-off depends on growth in value added per employee after the investment and on whether the investment is in a thematic area of the Smart Specialisation Strategy (S3). Below are the rules from the programme text, calculations for typical cases and what to prepare before the loan application, which opens on 20 November 2026 at 8:00.
Key points
- The write-off is 10% of the principal for every 2% growth in value added per employee, plus 5% if the investment is in an S3 thematic area, up to 50% of the amount used.
- Growth is measured in the financial year after the investment is completed, compared with the year before the loan application.
- The conditions are regular repayment and employment at least equal to the year before the application.
- The write-off is requested in writing and once, and principal already repaid is not written off.
- With a loan of EUR 100,000 at 0.5% the total interest is about EUR 2,800, while a 45% write-off is worth EUR 45,000.
Write-off rules in the programme text
The programme links the principal write-off to two criteria, connected with and/or, so they can be met separately or together.
- 10% of the principal for every 2% growth in value added per employee in the financial year after the investment is completed, compared with the year before the loan application
- 5% of the amount used if the result of the investment is in a thematic area of the Smart Specialisation Strategy until 2029
- in total no more than 50% of the principal used
- the conditions are regular repayment and total employment in the year after the investment at least equal to the year before the application
- the write-off is requested in writing and once during repayment, after the criteria are met, and principal already repaid cannot be written off
The method for calculating value added per employee is set by the programme text. It is therefore wise to calculate the baseline for the year before the application with your accountant before the loan application is submitted.
How large the write-off is depending on growth in value added
| Growth in value added per employee | Write-off without S3 | Write-off with S3 | Amount with a loan of EUR 100,000 |
|---|---|---|---|
| below 2% | 0% | 5% | EUR 0 or 5,000 |
| 2 to 3.9% | 10% | 15% | EUR 10,000 or 15,000 |
| 4 to 5.9% | 20% | 25% | EUR 20,000 or 25,000 |
| 6 to 7.9% | 30% | 35% | EUR 30,000 or 35,000 |
| 8 to 9.9% | 40% | 45% | EUR 40,000 or 45,000 |
| 10% or more | 50% | 50% | EUR 50,000 |
Why the timing of the write-off request matters
The write-off is calculated on the amount of the loan used, but principal already repaid is not written off. If the outstanding principal at the time of the request is lower than the calculated write-off, the difference cannot be obtained.
An example, assuming the longest term of 10 years, a one-year grace period and equal quarterly principal instalments. A loan of EUR 100,000 is disbursed in the first quarter of 2027, the investment is completed the same year and growth is measured for 2028. Annual financial statements for 2028 are filed by 30 April 2029. By mid-2029, 5 of 36 principal instalments have been paid, about EUR 86,100 remains and the write-off of EUR 45,000 can be obtained in full. The outstanding principal falls to EUR 50,000 only after 18 quarterly instalments, that is four and a half years of repayment.
So submit the write-off request as soon as the financial statements for the year after the investment are ready.
What the loan costs, with and without the write-off
The interest rate depends on the development group of the municipality or town of the investment, which you can check right away in the eligibility check. For comparison we use a bank loan at 4.5%, as an assumption, with the same term and repayment profile.
| Interest rate | Total interest, EUR 100,000 over 10 years with a one-year grace period | Difference from a loan at 4.5% |
|---|---|---|
| 0.5% (groups I to IV, hill and mountain areas, islands) | EUR 2,812.50 | EUR 22,500.00 less |
| 1% (groups V and VI) | EUR 5,625.00 | EUR 19,687.50 less |
| 1.5% (groups VII and VIII) | EUR 8,437.50 | EUR 16,875.00 less |
| bank loan at 4.5% (assumption) | EUR 25,312.50 |
The write-off comes on top of that difference. With a loan of EUR 100,000 at 0.5%, principal and interest together amount to EUR 102,812.50. With a 45% write-off total repayment falls below EUR 58,000, and interest after the write-off falls further because it is charged on a smaller principal.
What to prepare for the write-off when applying for the loan
- Calculate value added per employee and the number of employees for the year before the application. This is the baseline against which the year after the investment is compared.
- Describe the investment so that it is clear which priority niche and which thematic area of the Smart Specialisation Strategy until 2029 it belongs to, because the extra 5% depends on it.
- Plan employment. The number of employees in the year after the investment must not be lower than in the year before the application.
- Watch the deadlines. The loan must be used within 6 months of disbursement, and the write-off is requested once the results for the year after the investment are known.
- First of all, check your listing as a mapped stakeholder, because without it there is no loan.
Frequently asked questions
How much of the principal can be written off?
Up to 50% of the amount of the loan used. The write-off consists of 10% of the principal for every 2% growth in value added per employee and 5% for an investment in a thematic area of the Smart Specialisation Strategy (S3).
Which year is the growth in value added compared with?
The financial year after the investment is completed is compared with the year before the loan application.
Can the write-off be granted for S3 alone?
Yes. The programme links the rules with and/or, so an investment in an S3 thematic area brings a 5% write-off even without growth in value added, provided repayment is regular and employment is maintained.
When is the write-off requested?
In writing and once during repayment, after the criteria are met. Principal already repaid is not written off, so the request should be submitted as soon as the results for the year after the investment are known.
Can the number of employees fall?
Not if you want the write-off. Employment in the year after the investment is completed must be at least equal to employment in the year before the loan application.
Sources
- HAMAG-BICRO, programme text Mali zajmovi za industrijsku tranziciju (principal write-off, repayment terms)
- HAMAG-BICRO, Mali zajmovi za industrijsku tranziciju
- HAMAG-BICRO, reopening of the Small Loans for Industrial Transition, applications from 20 November 2026
PRINCIPAL WRITE-OFF
Let us calculate the write-off for your investment
Based on your financial statements we estimate value added per employee, the possible write-off and the cost of the loan, and prepare the application before 20 November. The first call is free of charge.